Inventory management for Philippine shops and cafés
Use worked stock worksheets for Philippine shops and cafés: convert cases to pieces, reconcile ingredient use, investigate count differences, and size supplier orders.

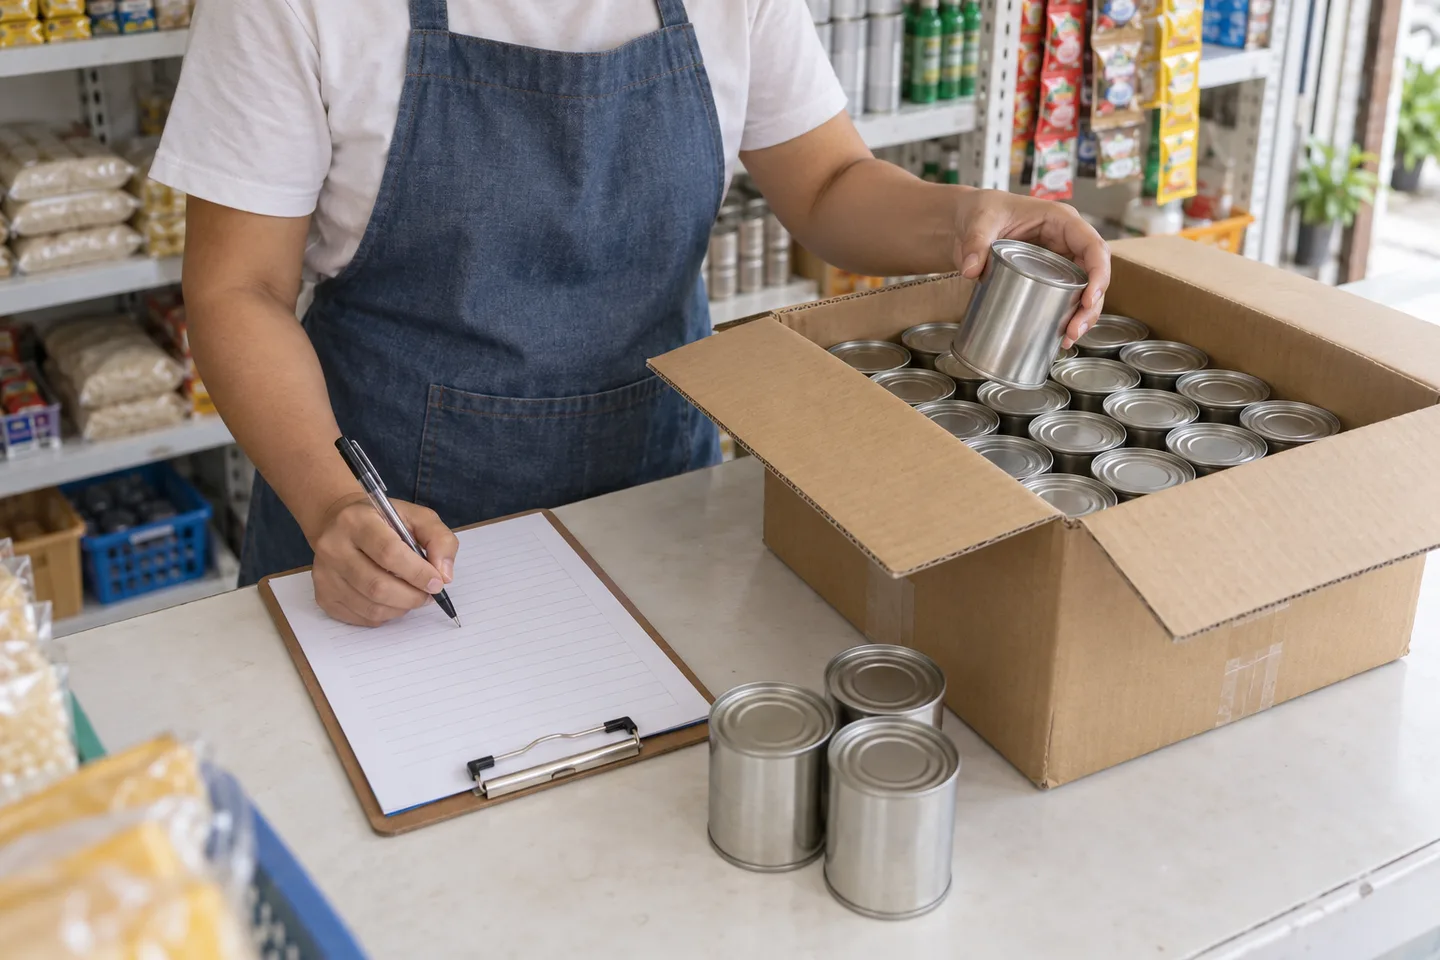
Inventory management means keeping track of what comes in, what goes out, and what is still available to sell. A workable routine starts with a consistent product list, a reliable opening count, and a record of every stock movement—not with a complicated spreadsheet.
For a sari-sari store, neighborhood retailer, or café in the Philippines, start with the units your team buys, stores, and sells. A delivery may arrive in cases while customers buy individual pieces; a café may buy ingredients in kilograms and use them by the gram. Build the record around those conversions and the supplier serving your location.
Use the stock movement worksheet to explain a count difference, the ingredient example to separate recipe use from recorded waste, and the order calculation to turn a stock target into supplier packs. These are illustrative operating records, not a tax inventory valuation method or merchant benchmarks.
Give each product one clear identity
Use a consistent name for each item and variant. “Milk” is ambiguous if you stock several sizes or types. “Whole milk, 1 L carton” tells the person counting exactly what belongs in that row.
Give each distinct item a simple stock-keeping unit (SKU). For example, MILK-WHOLE-1L can identify one product in a list. Your code does not need to describe everything; it needs to be unique and remain stable.
Keep these details together:
- Product name and SKU.
- Unit used for stock counts.
- Supplier and usual ordering unit.
- Storage location.
- Whether the product is active or discontinued.
Keep purchase and counting units explicit
If you buy cups by the case and count them individually, record how many cups are in one case. Check the supplier’s actual packaging rather than assuming every case is identical.
For a hypothetical sari-sari store, a case containing 24 bottles should add 24 bottles to stock when the store counts and sells by the bottle. Selling two leaves 22. If that product uses returnable bottles or crates, track the containers separately from the sellable drink and confirm the supplier’s return arrangement. Do not assume every brand or supplier uses the same pack size or deposit terms.
For ingredients, choose a unit your team can measure consistently. A partial bottle should not be counted as a full bottle on one shift and ignored on another. Write down the method alongside the product list.
Take a starting count before changing the system
Choose a quiet time and pause stock movements while you count, if practical. Separate sellable stock from damaged goods and items awaiting a return. Count one storage area at a time to avoid recording the same item twice.
Write down the date, time, and person responsible for the count. If sales or deliveries continue, record those movements separately so you can reconcile the result to a clear cutoff.
This becomes your opening balance. Keep a copy before importing it into any software.
Record every reason stock changes
A sale is only one reason that a quantity changes. Deliveries, customer returns, damage, spoilage, transfers, and internal use also need a record.
| Movement | Record at least |
|---|---|
| Supplier delivery | Item, received quantity, date, and delivery reference. |
| Sale | Item and quantity sold, linked to the transaction. |
| Customer return | Item, quantity, reference, and whether it can return to sellable stock. |
| Damage or spoilage | Quantity, reason, date, and person recording it. |
| Transfer | Quantity, origin, destination, and receiving confirmation. |
| Supplier return | Quantity physically sent back, date, and return reference. |
| Count correction | Original quantity, counted quantity, and reason for the adjustment. |
Do not replace a quantity without leaving a reason. The next count may look correct, but you will have lost the information needed to understand the difference.
A stock movement worksheet in pieces
Keep one row per movement, using the same SKU, unit, location, and cutoff. For sellable stock:
Expected closing units = opening units + accepted deliveries + sellable customer returns + transfers in − units sold − damage/internal use − supplier returns − transfers out.
This hypothetical bottled-drink example uses 24 bottles per case. Amounts are quantities, not pesos; returnable containers remain in a separate record.
| Movement at one shop | Change in bottles | Running sellable bottles |
|---|---|---|
| Opening count | +48 | 48 |
| Delivery: 2 cases × 24 bottles | +48 | 96 |
| Sales | −35 | 61 |
| Customer return accepted as sellable | +1 | 62 |
| Damaged bottles removed | −2 | 60 |
| Bottles physically returned to supplier | −4 | 56 |
| Transfer to another location | −6 | 50 |
| Physical count at cutoff | — | 49 |
Count variance = actual count − expected count = 49 − 50 = −1 bottle. A negative variance means fewer units were counted than recorded; a positive one means more. Recount and inspect movement references before posting a correction. If the one-bottle gap remains unresolved, retain expected 50, counted 49, adjustment −1, reason “unresolved after recount,” approver, and follow-up date. Do not relabel it as theft or spoilage without evidence.
A refund does not automatically put a product back on the shelf. Record the returned item’s disposition separately. Likewise, a supplier credit is a money record; only a physical movement changes this quantity worksheet. Keep goods awaiting inspection, damaged goods, and goods awaiting supplier return outside sellable stock and retain their separate record.
Reconcile café ingredients in their base unit
For a hypothetical café, 2 kg of opening beans plus a 1 kg delivery gives 3,000 g. If 60 drinks each use an 18 g recipe, expected recipe use is 60 × 18 = 1,080 g. With 120 g separately logged for dialing in the grinder and discarded coffee, expected closing beans are 3,000 − 1,080 − 120 = 1,800 g.
If the physical count is 1,750 g, the unexplained difference is −50 g, in addition to the 120 g already recorded. Check the count method, recipe portions, unrecorded drinks, and waste entries. Do not record the whole 170 g gap from recipe-only stock as new waste: that would count the logged 120 g twice. For several recipes, add each recipe’s drink count × grams used. Record staff drinks and remakes either through their recipes or as separate usage, once each.
TESDA’s Barista NC II training regulations, promulgated December 2013, include beginning/ending inventory, checking issued stock against requisitions, and monitoring stock levels (printed p. 41). The document remained listed by TESDA when checked September 12, 2026. It provides training context; the worksheet and numbers above are Sentra’s illustrative application, not a TESDA-prescribed form.
Use small, regular counts to find problems
A full stock count gives you a broad picture. A cycle count checks a smaller group of items on a recurring schedule.
Start with products that move quickly, expire soon, or have frequent differences. Count them at a consistent point in the day, compare them with the record, and investigate the largest gaps first.
Look for ordinary process issues before drawing conclusions: a delivery entered twice, the wrong pack size, a missed return, or a product sold under another item’s name. Document what you find and change the routine that caused it.
Set a reorder point you can explain
A reorder point is the stock level that prompts you to place an order. One planning approach is:
Reorder point = expected use during supplier lead time + a chosen stock buffer.
For an illustrative example, suppose a shop uses 30 cups a day, its supplier takes three days to deliver, and the owner chooses a buffer of 15 cups. The planning reorder point is (30 × 3) + 15, or 105 cups. These figures are hypothetical, not a recommended stock level for your business.
When checking the trigger, include confirmed incoming orders and subtract separate commitments not already in the demand forecast, as in the net-units calculation below. Check when incoming stock will arrive so you neither order the same shortage twice nor overlook a gap before delivery.
Use your own sales pattern, delivery history, shelf life, and storage limits. Revisit the number when demand or delivery times change. A buffer that helps a fast-moving shelf-stable product may create waste for a perishable ingredient.
Confirm delivery days and order cutoffs for your particular city or municipality. A café sourcing from a nearby wholesaler needs a different lead-time assumption from one whose supplier ships between islands. Ask how the supplier handles public holidays, weather interruptions, and missed delivery runs; use your own delivery records rather than assigning one lead time to all Philippine locations.
Calculate an order quantity for scheduled reviews
The 105-cup reorder point answers when to trigger an order if stock is monitored continually. It is not an instruction to buy 105 cups. If you instead review orders on a fixed schedule, a simple starting model covers both the delivery wait and the interval until the next review:
Target units = daily use × (lead-time days + review-interval days) + chosen buffer.
Net units to cover demand = usable on-hand units + confirmed incoming units − separately committed units.
Unrounded order = the greater of zero or (target units − net units).
Count commitments only if they are not already included in the demand forecast. Count an incoming order only once and check its arrival against when you need it. Match the day basis: if the supplier quotes working days, map those onto your actual trading calendar before multiplying by daily use.
| Hypothetical cup order input/output | Units or calculation |
|---|---|
| Daily use; lead time; review interval; buffer | 30 cups; 3 days; 7 days; 15 cups |
| Target | 30 × (3 + 7) + 15 = 315 cups |
| Usable on hand; confirmed incoming; separate commitment | 180 cups; 50 cups; 20 cups |
| Net units | 180 + 50 − 20 = 210 cups |
| Unrounded order | 315 − 210 = 105 cups |
| Supplier sells packs of 50 | Round up to 3 packs = 150 cups |
This scheduled review tops up toward a 315-cup target even though 210 net cups exceed the earlier continuous-review trigger. Choose one review policy deliberately. Do not run both calculations as separate orders. The 45-cup excess from pack rounding also occupies space and uses cash.
Before approving an order, check the delivery timeline, storage capacity, remaining usable life, minimum order, and available purchasing cash. For perishables, estimate what can be used before expiry; a mathematical target does not make excess milk usable. If stock will run out before delivery, a bigger order arriving on the same date cannot fix the gap: investigate a smaller earlier delivery, an alternative supplier, or a menu change.
Make one person responsible for reviewing exceptions
The whole team can record stock movements, but someone should own the follow-up. Set a regular review for unexplained adjustments, repeated stockouts, and items that are sitting too long.
Keep the review practical. Choose one issue, identify its cause, make a change, and check the result at the next count. Consistency matters more than an elaborate report nobody uses.
If you are evaluating software, bring this routine to the demo. Our guide to choosing a POS system includes the stock movements worth testing before you commit.
Practical knowledge. A clearer next step.
More from Sentra Insights